Key Takeaways
- A vehicle can lose resale value after an accident even when repairs restore its appearance and operation.[1]
- Repair costs and accident-related market value loss are separate issues.
- Vehicle age, mileage, prior damage, repair scope, repair quality, and local demand can affect the outcome.
- A formula may provide a starting estimate, but comparable market evidence can be more persuasive.
- Photos, invoices, history reports, and dealer offers can help document a possible loss.
- Insurance coverage, fault, state law, and claim deadlines may affect whether a claim can be pursued.
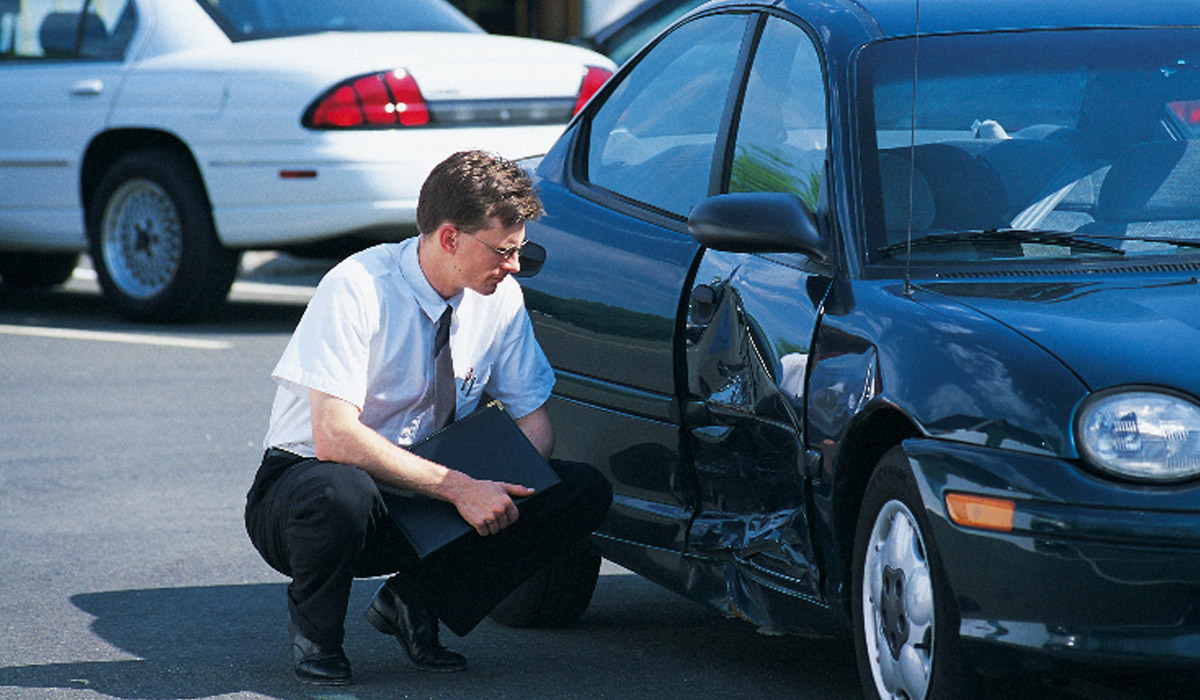
An accident can affect more than a car’s repair bill. Even after a vehicle has been repaired, an accident entry, visible repair history, or buyer concerns about prior damage may influence what someone is willing to pay. A diminished value calculator can provide an initial estimate, but it cannot replace a careful review of the vehicle and its local market.
The actual resale effect is not identical for every car. A newer vehicle with low mileage and a clean pre-accident record may face a different market reaction than an older vehicle with substantial mileage or several prior claims. The goal is to determine whether the vehicle’s market value after repairs is lower than it would likely have been without the collision.
What Resale-Value Loss Means
Resale-value loss, often called diminished value, is the difference between a vehicle’s market value before an accident and its market value after repair. It is separate from the cost of repairing damaged parts. Repairs address the vehicle’s physical condition, while diminished value assesses whether the market views the repaired vehicle differently from a comparable vehicle with no accident history.
The broader concept of diminished value applies to property that has been damaged and repaired but may still sell for less as a result of the event. For vehicles, the issue often becomes clear when a prospective buyer, dealer, or appraiser reviews the car’s condition and available history information.
Why Repairs May Not Restore Full Market Value
A high-quality repair can restore a vehicle’s appearance and may address damage identified during the repair process. It does not necessarily remove an accident record or eliminate buyer questions about what happened. Some buyers may be concerned about structural repairs, airbag deployment, replacement parts, paint work, electronic calibrations, or the possibility of damage that was not obvious at the time of sale.
For example, two otherwise similar late-model sedans may have the same trim, mileage, and equipment. If a car has a reported collision and repair history, a dealer or private buyer may offer less for it than for a comparable vehicle with a clean history. The price difference can vary widely, but the comparison illustrates why repair completion and market value are not the same.
Factors That Can Shape the Loss
Several vehicle-specific and market-specific details can affect whether there is a measurable reduction in resale value and how large it may be:
- Vehicle age and condition:Newer, well-maintained vehicles may have more value and be exposed to an accident-related discount.
- Mileage:Higher mileage may reduce the value at stake, but it does not automatically eliminate a loss.
- Pre-accident history:A clean history can make it easier to compare the vehicle’s condition before and after the collision.
- Damage severity:Damage involving structural components, airbags, multiple panels, suspension parts, or advanced driver-assistance systems may receive closer attention from buyers.
- Repair quality:Paint mismatch, panel gaps, warning lights, poor alignment, or incomplete documentation can reduce confidence in the repair.
- Vehicle type and demand:Market reactions can differ among economy vehicles, trucks, luxury models, specialty cars, and vehicles with limited local demand.
- Local conditions:Available inventory, seasonality, and regional pricing can affect comparable values.
How Insurers May Estimate Diminished Value
Insurers may use internal methods to evaluate a claimed loss. A basic process often begins with the vehicle’s estimated pre-accident value, applies a starting percentage or cap, and then adjusts the figure based on the severity of the damage and the vehicle’s mileage. The commonly discussed 17c method is one example of a formula-based approach, but it is not a universal measurement of every vehicle’s real-world market loss.[2]
- Estimate the vehicle’s pre-accident market value.
- Establish an initial potential loss figure.
- Adjust for the type and extent of damage.
- Apply a mileage-related adjustment.
- Review the result against repair records and available market evidence.
Why Formulas Have Limits
A standardized calculation may be useful for screening a claim, but it may not capture every relevant fact. Trim level, factory options, prior ownership, repair documentation, local inventory, vehicle popularity, and the details shown in a history report can all influence a buyer’s decision. Two vehicles with similar book values can produce different results if their accident histories and market comparisons differ.
For that reason, an estimate should be treated as a starting point rather than a final answer. Current comparable listings, written dealer appraisals, trade-in offers, and sales data can provide a more grounded picture of how the collision may affect the vehicle’s value.
Building a Useful Market Comparison
A meaningful comparison should focus on vehicles that are as similar as possible. Start by recording the subject vehicle’s year, make, model, trim, mileage, options, condition, and accident details. Then look for comparable vehicles with no reported accidents, as well as similar vehicles with accident histories.
- Use the same model year or a close range when necessary.
- Match trim, drivetrain, major options, and mileage as closely as possible.
- Prioritize listings and offers from the same region.
- Exclude vehicles with major differences, such as salvage branding or substantially different equipment.
- Save dated screenshots, written appraisals, and listing details.
- Consider both asking prices and actual dealer offers, as they may differ.
Records to Gather After a Collision
Documentation can help establish the vehicle’s pre-accident condition, the nature of the repairs, and the basis for a value comparison. The Federal Trade Commission notes that vehicle history reports may include accident and repair information, although buyers should not treat a history report as a substitute for an independent inspection.[3]
- Photos from before and after repairs
- Police or incident reports, when available
- Repair estimates, final invoices, and parts records
- Alignment, calibration, inspection, and diagnostic records
- Vehicle-history reports
- Pre-accident valuation records
- Comparable listings and written dealer offers
- Insurance correspondence and claim communications
When a Claim May Deserve Review
A closer review may be appropriate when another driver was responsible for the crash, the vehicle is relatively new or has significant pre-accident value, the accident is likely to appear in its history, or repairs involved more than minor cosmetic work. Whether compensation is available depends on the facts, applicable insurance coverage, fault, and the laws and deadlines that apply where the claim is made.
Not every vehicle will show a substantial measurable loss. Older cars, high-mileage vehicles, cars with prior accident history, and models with limited resale demand may have a smaller difference between their pre- and post-accident market values.
Common Questions About Post-Accident Value
Does a perfect repair restore full value?
It may restore the vehicle’s function and appearance, but it may not remove accident-related concerns or history information that can affect offers.
Is diminished value the same as normal depreciation?
No. Normal depreciation occurs as a vehicle ages and accumulates mileage. Accident-related loss is tied to the collision and its possible effect on market perception.
Can a minor accident affect resale value?
It can, although the impact may be limited. The result can depend on the reported damage, the repairs performed, the vehicle’s condition, and local buyer behavior.
Should the first insurance offer be accepted immediately?
Before accepting, it can be useful to review the valuation method, repair file, and available comparable evidence. A complete review helps clarify whether the offer reflects the specific vehicle and accident history.
Final Thoughts
A repaired car may look and drive much like it did before a collision, yet still receive lower resale or trade-in offers than a comparable vehicle with no accident history. Separating repair costs from potential market value loss, preserving repair records, and carefully comparing similar vehicles can provide a clearer basis for evaluating the vehicle’s market position.
References
[1] Insurance Information Institute. “What is diminished value?” Triple-I. The source explains that a vehicle involved in a major accident may have a lower resale value after repair than it would have had without the damage, even when repairs meet high-quality standards, and defines the difference as diminished value. https://www.iii.org/article/what-is-diminished-value
[2] National Association of Insurance Commissioners. “Inherent Diminished Value.” Journal of Insurance Regulation, 2023. The article describes the historically used 17(c) formula, including its use of a vehicle’s base value, a damage modifier, and a mileage modifier, while discussing limitations of diminished-value calculation methods. https://content.naic.org/sites/default/files/cipr-jir-2023-5.pdf
[3] Federal Trade Commission. “Used Cars.” Consumer Advice. The FTC states that vehicle history reports may include ownership history, accident information, and repair records, while also noting that a vehicle history report is not a substitute for an independent vehicle inspection. https://consumer.ftc.gov/features/feature-0040-used-cars